TL;DR
- Nothing happens by default. Paying rent will not build credit until a landlord or a service actively sets up rent reporting to credit bureaus.
- Rent reporting works best for tenants with minimal credit. Renters who already have credit files won't gain as much from rent reporting as tenants with little credit history.
- Check coverage before picking a reporting agency. Some services report to all three bureaus, while others report to only one or two.
- Landlords who offer rent reporting can attract more tenants and stand out compared to other rentals.
For renters, the reasons to pay rent on time are obvious: maintaining stable housing, saving money on late fees, creating good financial habits (the list goes on). However, there’s another perk that is not talked about as much — reporting on-time rent payments to credit bureaus for a credit boost.
In the era of digital rent collection, new tenants often ask, “Does paying rent build credit?” While it’s often overlooked by both tenants and landlords, the potential rewards can be valuable. And the reporting process itself couldn’t be easier with automatic rent reporting options.
If you’re a landlord considering offering this perk to renters or a tenant hoping rent will build credit, keep reading to learn about the pros and cons of the practice, how to set it up, and potential pitfalls to avoid.
Does paying rent build credit?
Rent appears on a credit report only if a landlord or service reports the payment record to a credit bureau.
Landlords are not required by law to report to credit bureaus, so without a reporting agreement, a tenant won’t be able to build good credit for rent, no matter how many years they pay on time.
In fact, fewer than 5% of tenants’ rent payments reach the bureaus, and in small rentals, only about 9% of tenants said the landlord reported their rent, per an Urban Institute analysis of a December 2023 survey of 2,241 renters.
Whether paying rent can build credit ultimately depends on whether or not the landlord has opted in. If a landlord doesn’t sign up for a reporting service or report payments themselves, they can still keep a detailed payment record in their rent roll and eventually report the information to credit bureaus.
How Rent Reporting Can Build Good Credit Lines
Landlords and tenants can turn on-time rent payments into credit report entries by following these steps:
- A platform or service records the payment with its date, amount, and whether it arrived on time.
- A registered data furnisher formats those records to the bureaus’ reporting specifications.
- The furnisher files them monthly with whichever bureaus it has agreements with.
- The bureau posts it as a credit account, also known as a tradeline, and it’s reflected in the renter’s payment history (which makes up 35% of a FICO score).
Since the length of one’s credit history makes up an additional 15% of a FICO score, reporting rent can do much more for tenants with limited credit. For tenants who already have good credit and a solid, extensive history, rent reporting may not move the needle as much as they’d hoped.
Important note: Credit bureaus accept payment data only from registered data furnishers, which require a merchant account and meet certain transaction thresholds. Simply collecting rent online doesn’t automatically make a landlord eligible for the service.
Which Bureaus Take Rent Data?
There are three major credit bureaus: TransUnion, Equifax, and Experian. All three companies collect financial data and provide it to credit card companies and lenders.
Where rent payments are reported depends on which rent reporting service you use. Tenants can report payments through a variety of ways, including reporting through a credit bureau directly.
To make it easy for landlords and tenants to get the most out of paying rent, many property management software include rent reporting options with rent collection. Some report to all three main credit bureaus, while others report to only one or two.
To make sure rent reporting will be worthwhile, check whether a scoring model will include rent payment data.
| Scoring model | Reads rent payment data | Where a lender uses it |
|---|---|---|
| Classic FICO (versions 2, 4, and 5) | No | Fannie Mae and Freddie Mac require these versions |
| FICO Score 9 | Yes | FICO has included rental data in every new version since 2014 |
| FICO 10T | Yes | Approved but not yet in use; historical scores due summer 2026 |
| VantageScore 4.0 | Yes | Approved for loans sold to Fannie Mae and Freddie Mac |
Different lenders require different scoring models, some of which may not include rental data at all. Your tenant can find out whether their lender considers rental data by asking a loan officer which version of the FICO score they pull.
How to Report Rent Payments to Credit Bureaus
Rent can appear on a credit report in one of the three ways below, depending on whether the landlord reports it. Without their landlord’s cooperation, though, the tenant would have to obtain the service and link their bank accounts themselves.
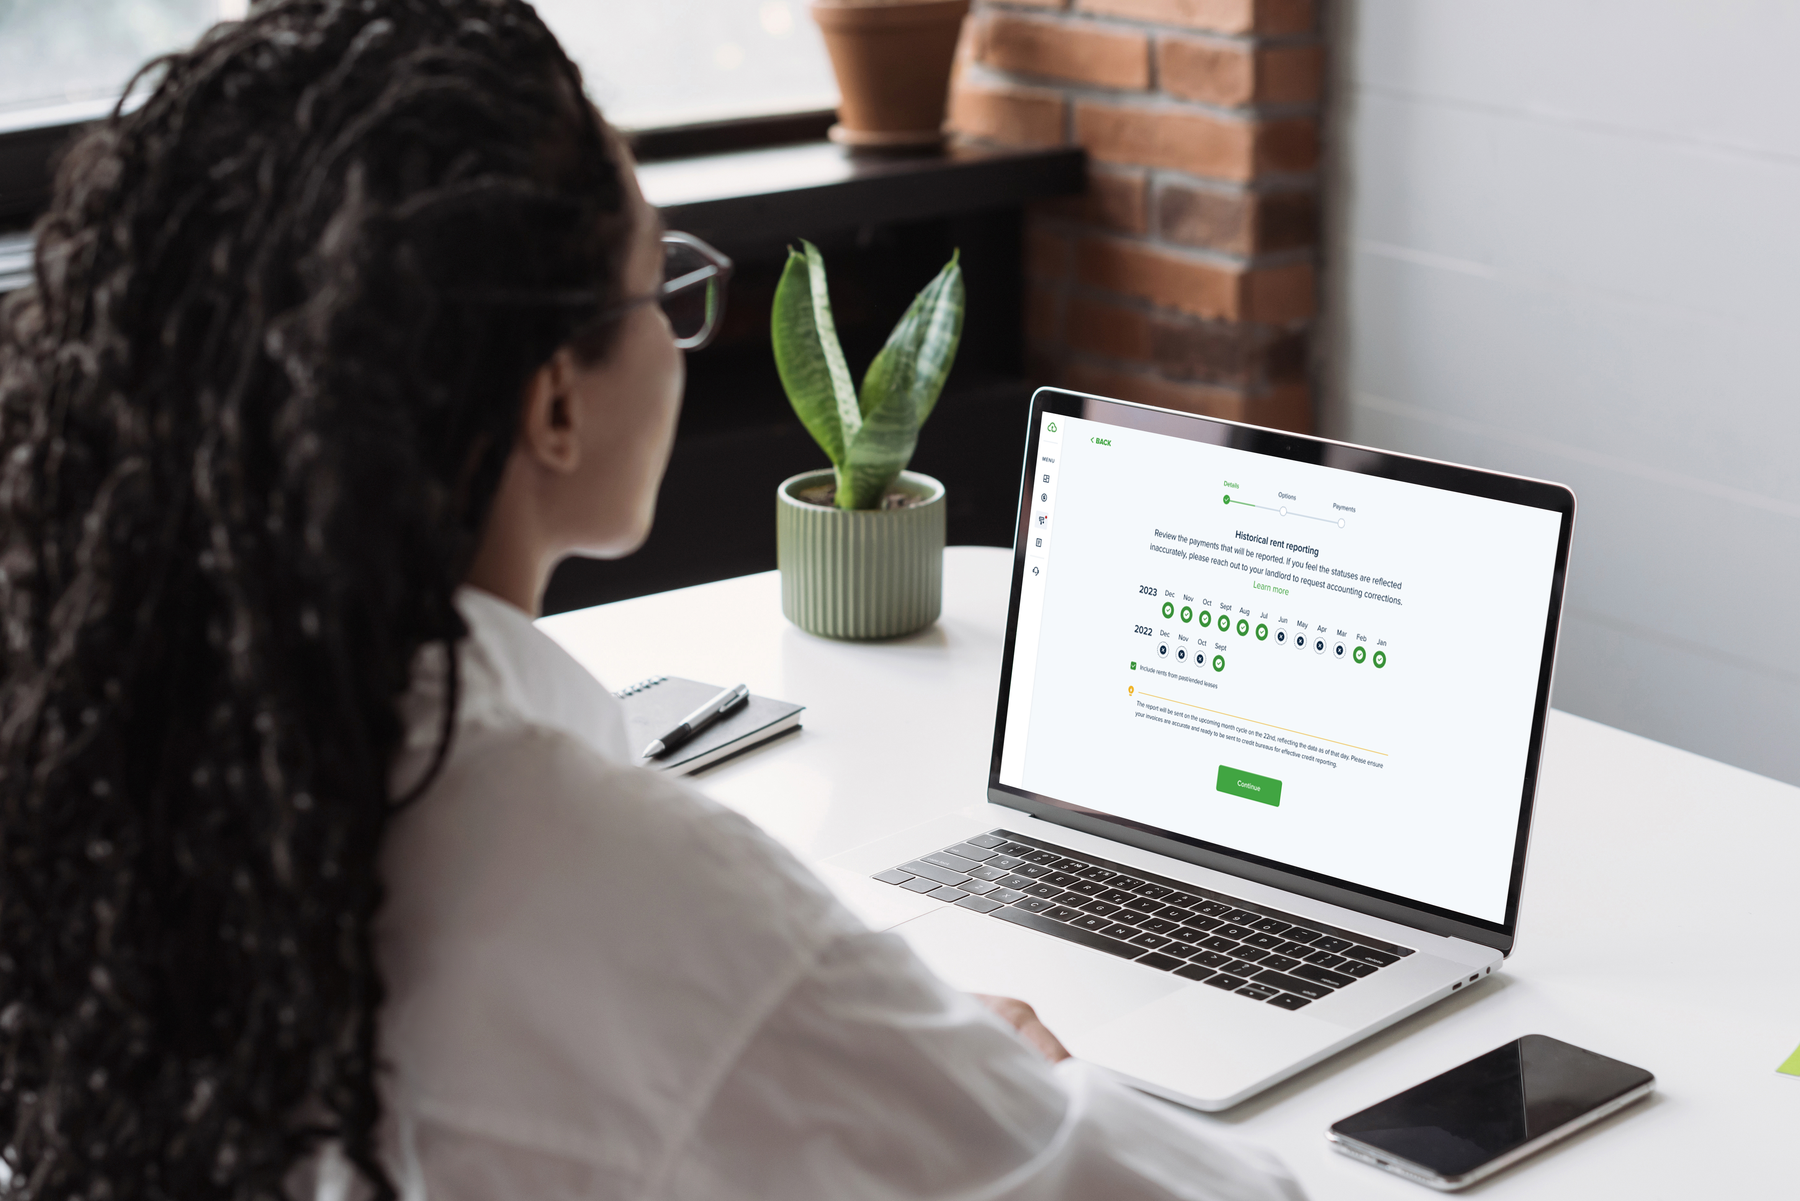
Some property management software includes rent reporting to credit bureaus built-in, so tenants simply need to decide whether to allow landlords to report their rent.
| Route | Who turns it on | Bureaus it reaches | What the landlord has to do |
|---|---|---|---|
| Property management platform | Landlord enables, tenant opts in | Varies by platform | Enable rent reporting via the software, then let tenants decide |
| Tenant-paid standalone service | The tenant, independently | Varies by service | Confirm the tenancy if the service asks |
| Experian Boost | The tenant, by linking a bank account | Experian only | Nothing |
Standalone services like Rental Kharma, RentReporters, and LevelCredit work directly with the tenant, while others first confirm the tenancy with the landlord. Some platforms also offer back-reporting, which uses historical records to report previous on-time payments.
Rent Reporting Benefits for Landlords
Finding and using a rent reporting service for tenants can have tangible benefits for landlords. For starters, it’s a helpful incentive for tenants to pay rent on time every month, build credit, and prevent damage. When tenants pay on time more often, landlords win. It’s not complicated.
A September 2025 report from TransUnion found that 57% of renters prefer a property manager who offers rent reporting, and nearly 80% say they pay on time more reliably. Offering the feature also gives landlords an edge over the competition, as the share of property managers with rent reporting fell from 48% in 2024 to 44% in 2025.
With all this in mind, tenants will only opt in to rent reporting if someone tells them the feature exists. If you’re a landlord who offers the service, you may want to mention it in the property listing and remind new renters of the feature. Since not everyone is familiar with rent reporting, communication is key.
Ideally, the rent reporting service you choose should allow tenant authorization, automatic digital tracking, and data correction for potentially inaccurate entries. As you do your research, also find out whether late payments are reported to the credit bureaus.
Is rent reporting worth the cost?
Rent reporting is typically a small, monthly cost to the tenant, which covers the reporting fees. In the case of using a property management platform to report, a tenant opts into a monthly fee, and the landlord’s side is covered by the software subscription they already pay for.
At the free end of the spectrum, Experian Boost reports rent to one bureau. Tenant-paid standalone services run roughly $3 to $11 a month as of mid-2026, with one-time setup or back-reporting fees around $50 to $95. Reporting built into property management platforms usually costs tenants about $5 a month.
While not typically free, rent reporting will provide significant value to tenants who need all the help they can get to build their credit. For landlords, it could be the difference between securing a good tenant and having them look towards their competition for a rental that supports reporting.
What Can Go Wrong: After Tenants Enroll in Rent Reporting
First, if anything gets mixed up during rent reporting, your tenant might not find out right away (though they can check by pulling a free report at AnnualCreditReport.com 60 days after enrolling). In the early stages, both landlords and tenants should monitor the reports to ensure they’re accurate.
Also, a June 2025 study found that 27% of tenants who tried to sign up for rent reporting never got past eligibility or enrollment, and 30% of those eligible had no rent reported at all.
These issues stem from a few different common problems:
- Ineligibility at signup prevents rent reporting if the lease agreement isn’t in the tenant’s name or if the service doesn’t operate in your state. Check with the reporting agency before getting started.
- After the tenant enrolls, confirm the service is actually furnishing reports to the credit bureaus as it claims.
- If you use a service that only reports to one bureau, the rent data won’t show up on the other two bureaus’ reports.
- Late payments may not appear on credit reports if the service only does positive rent reporting.
Report On-Time Rent and Reward Your Best Tenants
Paying rent can easily build good credit, but only if the landlord or tenant opts in to a rent reporting service. Either way, both parties should do their research before signing up to ensure an agency reports to the right credit bureaus and includes negative payment history.
Most landlords who offer rent reporting use property management software that relies on online rent collection, another major benefit for tenants. Offering your renters these services will improve landlord-tenant relationships with minimal effort on your end.
Sign up for a free 14-day TenantCloud trial to turn your tenants’ on-time payments into credit history they can actually use.
Frequently Asked Questions
How long does rent reporting take to show up on a credit report?
Credit furnishers send updates in monthly batches rather than in real time, so the new account should appear after the first reporting cycle. Any back-reported rent payment history will arrive in that same batch.
Can rent be reported to all three credit bureaus?
Some rent reporting services cover all three credit bureaus, but many report to only one. So, it comes down to the specific service you choose. RentReporters and LevelCredit report to all three, while Experian Boost only reports to Experian.
Can paying rent late hurt a tenant's credit?
Yes, as long as the reporting service reports both negative and positive payments. If the reporting service only covers positive payments, tenants may be able to pay rent late without damaging their credit scores.
Additionally, extremely late rent payments sent to collections will also damage a renter’s credit.
What happens to rent reporting when a tenant moves out?
Rent reporting ends as soon as the lease does, but the tradeline typically stays on the tenant’s credit history. A tenant who wants to continue rent reporting must re-enroll at their new address because these services usually require the renter to verify their tenancy.
Can a tenant report rent from a previous apartment?
Sometimes, depending on the service. RentReporters covers up to 2 years on the current lease and up to 4 years total, including recent previous leases, while other services only offer rent reporting for the tenant’s current address.